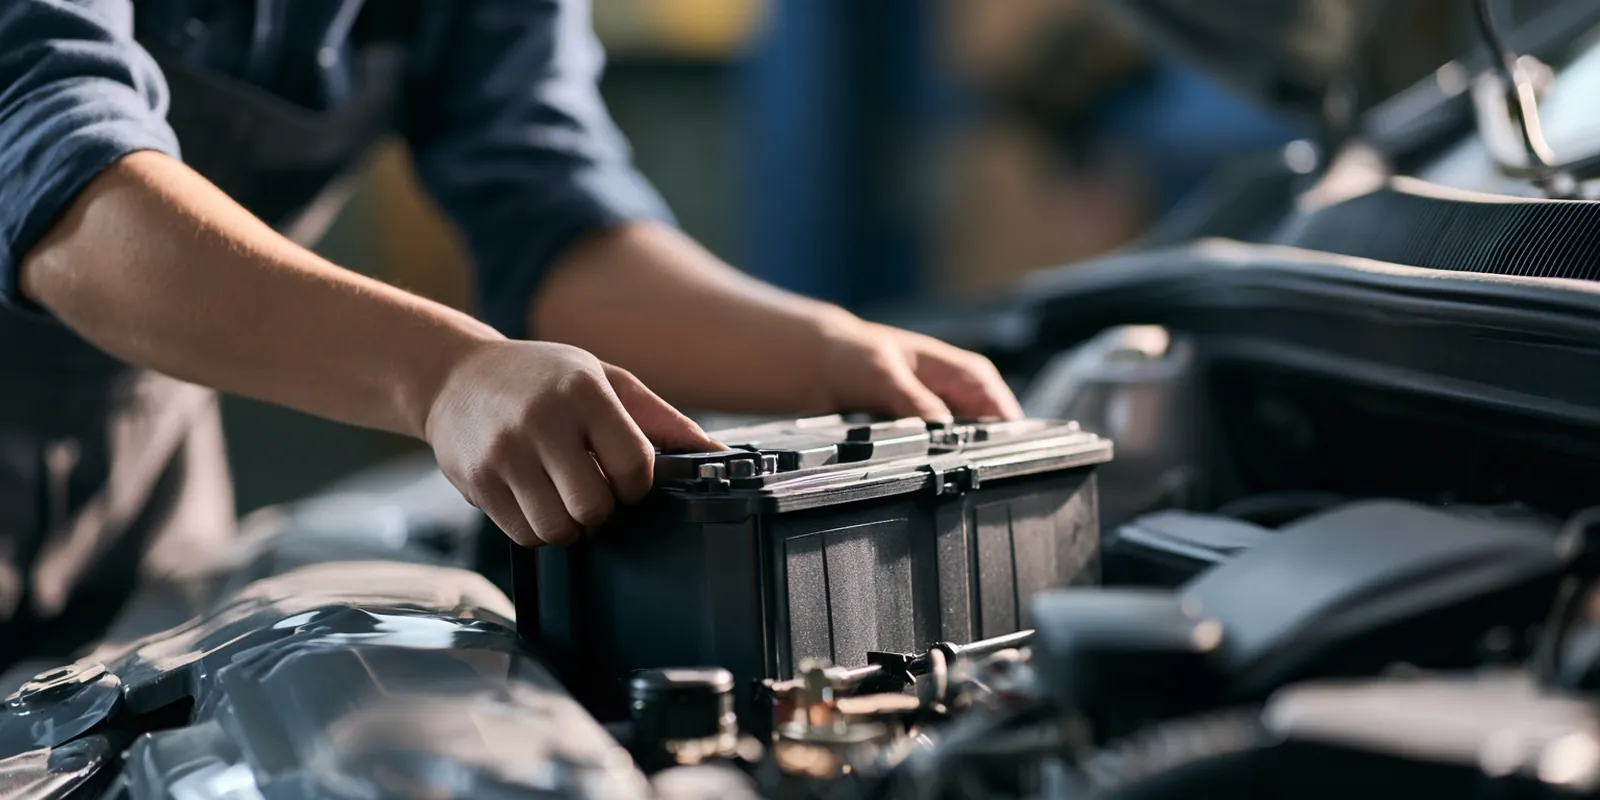
A $500 loan is the smallest amount you can request through our form. It is built for the bills that are too big for one paycheck but too small for a large personal loan: a dead battery on a cold morning, a sick dog, a shutoff notice taped to the door. You fill out one request, it goes to lenders in our network, and any offers come back for you to review with no obligation.
People researching avant lending at this size usually want two answers fast. Can I borrow this little, and what will a $500 loan really cost? This page covers both, plus the honest part many sites skip: fewer lenders make personal loans this small, and sometimes a cheaper option is sitting right in your own town.
Estimates for a $500 loan at 24.99% APR with no origination fee. Your APR, fees and payment are set by the lender in your offer.
Who Typically Borrows a $500 Loan
Borrowers who request a $500 loan usually have steady income but no cushion. A single surprise bill would push their checking account negative, and they want a fixed payment they can clear within a few months instead of carrying a card balance.
The profile is ordinary. A warehouse worker paid every two weeks. A home health aide whose car is her job. A parent who just covered back-to-school costs and then got hit with something else. Most are not using a personal loan to fund a project. They are trying to stop a small problem from becoming a bigger one, like a missed shift, a late fee, or a reconnection charge.
A small personal loan also appeals to people who have been burned by revolving credit. A card lets the balance linger for years. A personal loan of a few hundred dollars has an end date printed in the agreement, which makes it easier to plan around. That is a big part of why avant lending searches at this amount often come from people who simply want the debt gone by a set month.
Four Common Uses for a 500 Dollar Loan
A 500 dollar loan most often covers one urgent, fixed-price bill: a car battery or tire, a vet visit, an overdue utility balance, or a medical co-pay. Each has a clear dollar figure, which makes it easy to borrow only what you need.
A dead car battery or a blown tire
A replacement battery installed at a shop often runs $150 to $350 depending on the car, and a newer vehicle with start-stop technology can need a pricier AGM battery. One tire with mounting and balancing lands in a similar range, and a pair can approach the full amount. If the car gets you to work, a $500 loan that keeps you on the road for one more pay period can pay for itself in saved wages.
A vet visit for a sick dog
An exam fee, bloodwork and medication for a dog that stopped eating can reach $300 to $600 at a general practice, and more at an emergency clinic. Ask for a written estimate before treatment starts. Many clinics will split it into must-do-today and can-wait items, which can shrink the personal loan you need.
A utility shutoff notice
Past-due electric, gas or water bills often come with a reconnection fee on top of the balance. Paying before the shutoff date avoids that fee and a possible deposit. Call the utility first, though. Many offer payment arrangements or hardship programs that could cut the size of your $500 loan request, or remove the need entirely.
A co-pay or out-of-pocket medical bill
An urgent care visit, an imaging co-pay, or the first part of a deductible can arrive as a bill for a few hundred dollars. Before applying for a personal loan, ask the provider for an itemized bill and whether they offer an interest-free payment plan. Many hospitals and clinics do, and a no-interest plan will beat any personal loan on cost.
Why Fewer Lenders Offer a $500 Loan
Many online lenders set their minimum loan at $1,000 or higher, so a $500 loan request reaches a smaller group of lenders. You may see fewer offers, or none, even with decent credit. Approving and servicing a loan costs a lender about the same at any size.
We would rather tell you this up front than have you wonder why your avant lending results look thin. Lenders who do make personal loans at this size tend to keep terms short, often 3 to 12 months, and some price small loans higher to cover their fixed costs.
If your bill is closer to $800 or $900, our page on the $1,000 loan amount and its payment estimates shows how the numbers change one step up. Do not inflate your avant lending request just to unlock more offers, though. Borrowing an extra $500 you do not need adds real interest over a year and raises the monthly payment you must carry.
A thin result is a signal to check the alternatives later on this page, not a verdict on your finances.
Estimated Payments on a $500 Loan
A $500 loan at 24.99% APR with no origination fee comes to about $89.51 a month over 6 months, or about $47.52 a month over 12 months. The longer term lowers the payment but nearly doubles the interest.
The cards above show 6, 12 and 18 month personal loan figures at a single rate. The table below adds a lower and a higher APR and two shorter terms, so you can see how much the rate and length move the total. Your real APR depends on your credit, income and the lender, so check our page on typical personal loan APR ranges before you judge any offer.
| APR | Term | Monthly payment | Total interest |
|---|---|---|---|
| 14.99% | 3 months | $170.85 | $12.55 |
| 14.99% | 12 months | $45.13 | $41.56 |
| 24.99% | 3 months | $173.66 | $20.98 |
| 24.99% | 9 months | $61.50 | $53.50 |
| 35.99% | 6 months | $92.30 | $53.80 |
| 35.99% | 12 months | $50.23 | $102.76 |
Estimates only, calculated with standard amortization and no fees. Your actual APR, term and payment come from the lender's offer.
Notice the pattern. At 35.99% over a year you pay about $102.76 in interest, roughly a fifth of what you borrowed. At 14.99% over 3 months you pay about $12.55. If you can handle a payment near $170, a short term saves the most on a 500 dollar loan. Our personal loan calculator lets you try your own rate and term in seconds, which is the fastest way to answer most avant lending questions about cost.
Costs and Fees to Check Before You Sign
The APR is the best single number for comparing small personal loans because it folds in interest and most required fees. On a $500 loan, an origination fee or a late fee hits harder than on a larger balance, so read every line.
- Origination fee. Some lenders deduct 1% to 10% from the proceeds. At 8%, that is $40 off the top, so you would receive $460. If you need the full amount in hand, ask whether the fee is deducted or added.
- Late fees. A flat late fee of $15 or $25 is a big share of a payment under $100. Set up autopay for a day or two after your paycheck lands.
- Returned payment fees. A payment that bounces can trigger a lender fee and a bank fee at once.
- Prepayment terms. Many personal loans let you pay early with no penalty. Confirm it, because paying off a small balance early is one of the easiest ways to save.
Readers who search avant lending reviews often focus on star ratings. A more useful habit is to pull up the CFPB complaint database and look for patterns about fees and payment processing for any lender behind a personal loan offer you are weighing.
Documents and Conditions Lenders Commonly Ask For
Lenders making a small personal loan usually verify identity, income and a bank account. Expect to confirm you are at least 18 (19 in Alabama and Nebraska), a U.S. citizen or permanent resident, and that you have a valid Social Security number.
- A government-issued photo ID, such as a driver's license or state ID card.
- Proof of steady income: recent pay stubs, a benefits letter, or bank statements showing regular deposits.
- A checking account in your own name, used for the personal loan deposit and often for autopay.
- A working email address and phone number for verification codes and the loan agreement.
- Your home address, sometimes confirmed with a utility bill or lease.
Many lenders begin with a soft inquiry that does not affect your credit score. Accepting a personal loan offer may lead to a hard inquiry, depending on the lender. Our eligibility requirements guide explains each condition, including what lenders look for in income and bank history. Having these items ready makes an avant lending request for a small amount move faster.
Short-Term Loan vs. Cheaper Alternatives
For $500, a short personal loan is only one option. An employer paycheck advance, local assistance programs, or a credit union small-dollar loan can cost less, and some cost nothing at all. Check them in that order if time allows.
A paycheck advance from your employer
Some employers will advance part of wages you have already earned, either through payroll or through an earned-wage app they provide. Employer advances are often free or carry a small flat fee, which beats most personal loans on cost. The tradeoff is a smaller next paycheck, so plan for the gap. Ask HR or your manager plainly; it is a more common request than most people assume.
Local assistance and hardship programs
For utility bills, dialing 211 connects you to local help, including energy assistance funds and charities that pay part of a past-due balance. Utility companies often run their own hardship programs. For vet bills, some animal welfare groups offer small grants, and veterinary schools may offer lower-cost care. None of these show up on a credit report the way personal loans do.
A credit union small-dollar loan
Federal credit unions can offer small-dollar loans with APRs capped at 28%, usually with terms of one to twelve months and a modest application fee. You typically need to be a member, and some require membership for a short time first. If you already belong to a credit union, call and ask before you request a personal loan anywhere else.
| Option | Typical cost | Speed | Main catch |
|---|---|---|---|
| Short personal loan | APR from about 5.99% to 35.99%, sometimes higher | Often next business day | Fewer lenders at $500 |
| Employer paycheck advance | Often free or a small fee | Same day to a few days | Smaller next paycheck |
| Local assistance | Usually free | Days to weeks | Limited funds, paperwork |
| Credit union small-dollar loan | APR capped at 28% | Same day to a week | Membership required |
A $500 loan through our form still makes sense when the cheaper options fall through or the timing does not work. A tire you need tomorrow will not wait three weeks for a charity to review an application, and an avant cash loan search at midnight usually means the clock matters.
When a $500 Loan Is the Wrong Move
Skip borrowing if the payment would squeeze your next month so hard that you need another loan to cover it. A $500 loan should solve one problem, not start a cycle of borrowing to pay off borrowing.
- The bill can be negotiated. Medical providers and utilities often accept payment plans with no interest. Ask before you borrow.
- The cost is recurring. If you are short every month on rent or groceries, a personal loan treats the symptom. A budget review or a benefits check is a better first step.
- You already have several open loans. Stacking small personal loans makes due dates hard to track and late fees more likely.
- The offer's APR is far above 36%. Some lenders quote higher where state law allows. Compare that 500 dollar loan offer with the alternatives above before signing.
Saying no to an offer is free. Nothing about an avant lending request commits you to borrowing.
Next Steps for Your $500 Loan Request
Start by pinning down the exact amount, then check one cheaper option, then send a request if you still need the money. Most people can finish all three steps in under an hour.
- Get the real number. Ask the shop, clinic or utility for a written total, including taxes and fees.
- Make one call. Try your employer, your credit union or 211. A ten-minute call can save you the interest.
- Check your budget. Decide the highest monthly payment you can cover without missing another bill.
- Send one request. Our form is free and takes a few minutes. People who type "avant loan application" into a search bar often expect a single lender; our service instead shares your request with lenders in our network.
- Compare offers carefully. Look at the APR, any origination fee, the term and the total repaid. An avant lending request is only useful if the offer fits the budget you set in step three.
We are not a lender, we do not set rates, and we may be paid by the lenders who make personal loan offers. There is no fee to submit your $500 loan request and no obligation to accept anything you receive.
Frequently Asked Questions
Can I get a $500 loan with bad credit?
Some lenders consider fair or poor credit at this amount, usually with a higher APR and a shorter term. Steady income and a checking account in your name matter a lot. A soft-inquiry check lets you see whether any personal loan offer appears before you commit to anything, and you can always decline.
How fast could the money arrive?
After approval and a signed agreement, many lenders deposit funds as soon as the next business day. Some take a few business days, and requests sent late on a Friday or before a holiday usually land later. If the bill is due tomorrow, call the provider and ask for a short extension while you wait.
Why do I see more offers when I ask for more money?
Many lenders set a minimum loan of $1,000 because underwriting and servicing cost about the same at any size. A 500 dollar loan request may therefore reach fewer lenders, which is one of the most common avant lending questions at this size. Asking for more than you need only to get offers usually means paying interest on money you never planned to spend.
Is a $500 loan better than a credit card cash advance?
Often, yes. Cash advances usually start charging interest the same day, add a fee of around 3% to 5%, and carry a higher APR than regular purchases. A fixed-rate personal loan gives you a set payment and end date. Compare the total cost of both in dollars before choosing.